Guarding the Guard: Why Every CFO Needs an Independent Auditor
Summary
True financial governance relies on separating powers and creating an independent internal audit reporting to the board to shield family businesses from self-policing risks.
When asked how errors and discrepancies are detected within the finance department, a Chief Financial Officer typically responds with complete confidence that daily internal controls handle the task under their supervision. Yet the crucial question rarely asked in boardrooms is: who catches the CFO's own mistakes when they occur? This simple inquiry pierces the illusion of absolute transparency assumed by most executive teams. Human error and flawed accounting estimates are not remote possibilities; they are concrete realities that have accompanied corporate financial operations throughout business history.
Sound corporate governance is never built on good intentions or the presumed infallibility of executives regarding oversight, bias, or misjudgment. Practical governance relies instead on robust institutional mechanisms capable of uncovering financial irregularities early and correcting them before they escalate into solvency-threatening losses. In the absence of such independent mechanisms, financial control degrades into a superficial exercise where executives audit their own work—a model with fundamental risks that directly impair the accuracy of financial statements and the reliability of investment decisions.
This oversight gap is nowhere more pronounced than in family businesses that have scaled their operations without expanding their governance structures accordingly. In many such companies, financial leaders enjoy long-standing, unquestioned trust from business owners, rooted in decades of personal history or loyal service. While valuable on a human and management level, this trust becomes a dangerous vulnerability when it replaces objective, independent oversight. An executive tasked with reviewing their own performance naturally notices evidence supporting prior assumptions while overlooking imbalances that might weaken their executive standing.
Here lies a core tenet of modern management theory: self-policing is inherently incomplete and fails to offer adequate organizational protection. Safeguarding a company's financial framework requires protecting the finance function itself from its own cognitive biases and daily operational pressures. Achieving this requires establishing an independent oversight body empowered to examine financial activities with absolute neutrality. That mechanism is an internal audit function structurally and functionally independent of executive management, reporting directly to the board's audit committee.
Organizational Independence as a Prerequisite for Effectiveness
Organizational independence dictates that internal auditors must not report to or fall under the authority of the CFO or any other executive officer. When an internal auditor reports hierarchically to the CFO—or relies on them for performance evaluations and bonuses—the audit process loses its essential value, becoming a mere rubber-stamping exercise for management decisions. An auditor who feels their job security depends on pleasing the individual they audit cannot objectively report material deficiencies. Direct reporting to the audit committee is therefore indispensable for preserving the integrity of the supervisory process.
This independence has become increasingly critical given the complexity of modern accounting transactions and the heavy reliance on discretionary judgment when preparing financial statements. Such estimates involve asset valuations, bad debt provisions, and future liabilities arising from operational contracts. Each area carries a wide margin for error or selective accounting designed to present a more stable balance sheet than reality warrants. An independent audit serves as a vital safeguard, insulating these judgments from bias or unwarranted exaggeration.
Across many family-owned enterprises in the Arab world, introducing an independent audit system and an active audit committee is often misconstrued as a vote of no confidence in the CFO's integrity. This misconception remains a major obstacle to transitioning family businesses toward sustainable corporate governance. The primary objective of independent oversight is not to seek out personal flaws or assign blame, but to create a professional framework that shields both the institution and its executives from the legal and financial exposure of individual decisions. A rigorous governance model provides a competent CFO with a secure framework that validates their figures.
Balancing Administrative Costs and Institutional Accountability
Some business owners and executives argue that adding layers of independent audit bureaucracy slows decision-making and imposes unnecessary overhead on operating budgets. They contend that hiring a highly competent CFO with a proven track record is sufficient to safeguard the business and drive growth, rendering independent audit committees redundant. This view stems from an understandable desire to streamline operations, reduce administrative complexity, and curb expenses that yield no immediate, direct return on revenue or profit.
However, a thorough analysis of financial risk demonstrates that the cost of failing to maintain independent oversight far exceeds the expense of establishing an internal audit department and board-level audit committee. Compounding accounting errors or flawed cash flow forecasts can cause sudden insolvency and erode market valuation. Moreover, independent controls significantly enhance the confidence of lenders, financial institutions, and external investors in a company's reported numbers.
Transitioning from trust-based management to institutional accountability is essential for long-term sustainability and asset protection during generational transitions in family enterprises. Companies that tie their financial health entirely to an individual CFO remain structurally vulnerable to leadership turnover, retirement, or errors of judgment. Independent governance ensures control mechanisms endure across generations as permanent institutional assets unaffected by executive departures or operational shifts.
Ultimately, corporate governance reflects the understanding that oversight is not a punitive measure but a core component of organizational safety. A confident finance function welcomes independent internal audit to validate its work and protect its decisions from scrutiny. Combining executive authority and supervisory control in a single role creates a vulnerability that has historically cost companies dearly. True protection for corporate assets is protection that is itself subject to independent, uncompromising oversight.
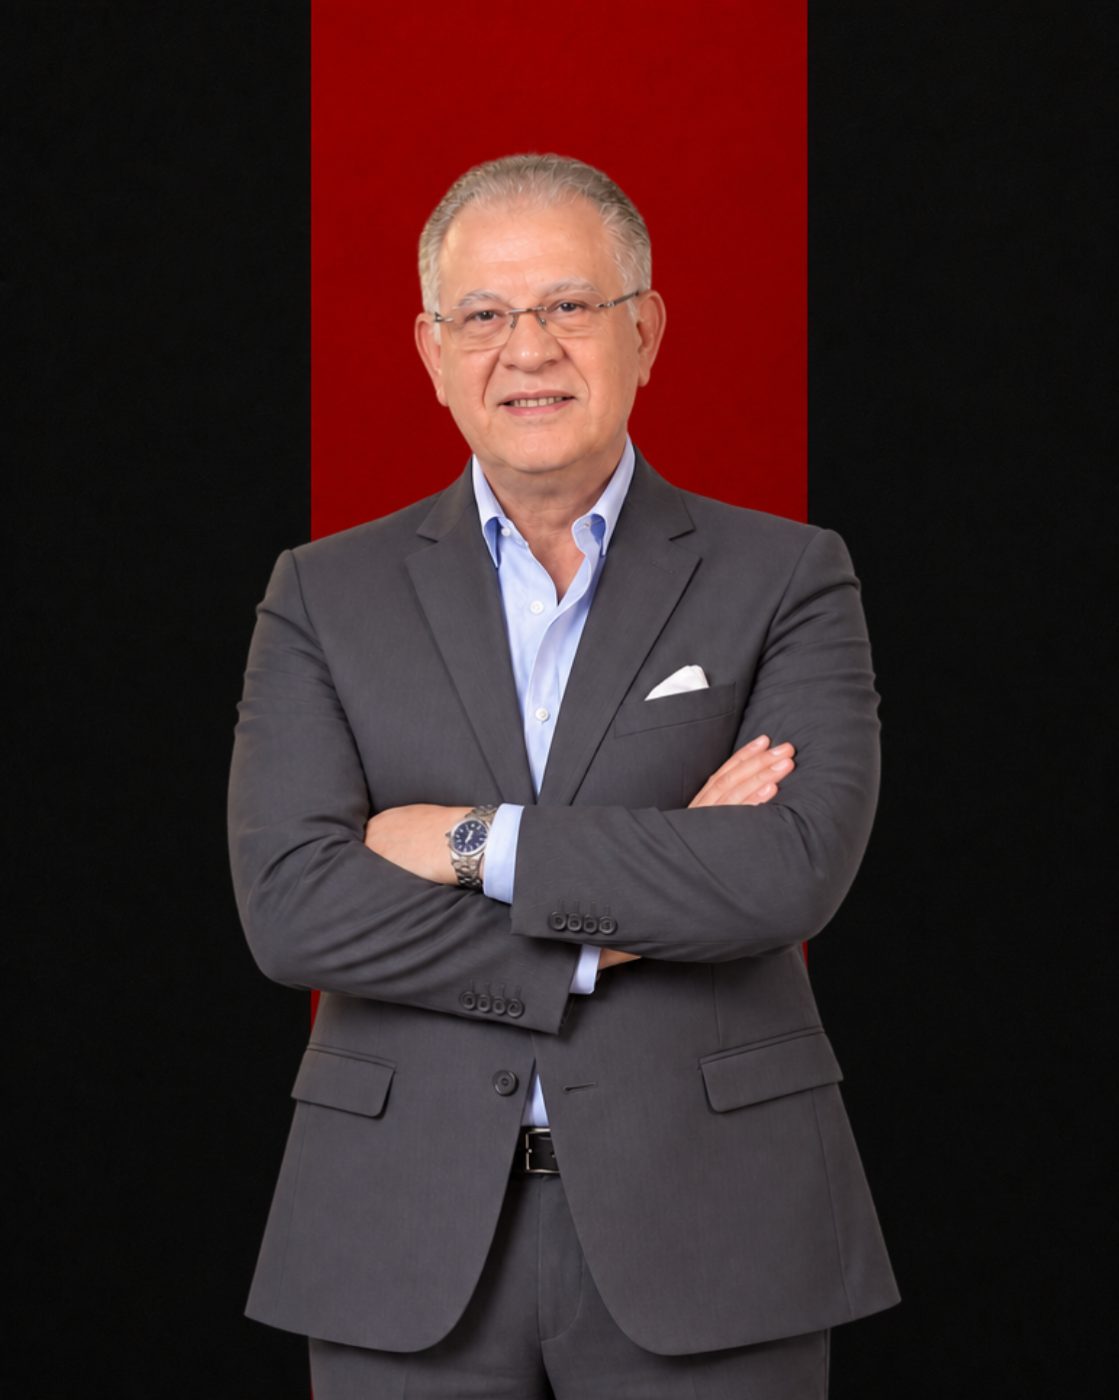
Dr. Hazem Farouk El Mahdi Business Management and Corporate Governance Consultant, and an expert in Business Strategy and Profitability Optimization, with 38+ years of experience in management, marketing, sales, operations, and business development. His expertise focuses on corporate restructuring, governance, family business development, strategic planning, performance improvement, profitability optimization, and leadership development, with professional and consulting experience across Egypt and the Arab markets. He is the founder of the PIOS™ Model and G-Road™ Business Governance Methodology, and the developer of several professional frameworks for organizational diagnosis, profitability optimization, and performance improvement. He is also the author of “Family Businesses: From Conflict to Sustainability.”
Profile and all their articlesThe Family Business Arabia
Weekly Newsletter
Read between the lines before everyone else. Decode the most important economic, tech, and decision-maker movements in the region.. in 5 minutes every Saturday.