Saudi CMA's Leverage Cap on Foreign Trading: Protection or Paternalism?
Summary
Saudi CMA proposes 50% and 25% margins on Saudi brokers' foreign market trades. The rule caps leverage but won't restore local market liquidity.
After more than 20 years of following financial markets and their regulatory bodies, I learned that the most dangerous numbers are not the huge ones, but those that do not align with their neighbors. In the Saudi Capital Market Authority data, there are two such numbers: foreign trading of about 939 billion riyals in the twelve months ending in the first quarter, against client assets of about 36.5 billion riyals. That is, the trading value equals 25.7 times the value of assets. This ratio proves neither speculation nor borrowing, but it explains why the Authority has begun looking at what is happening outside borders.
The issue is bigger than brokers' figures; Saudi Tadawul is the largest financial market in the Middle East and North Africa, with its main market companies' market capitalization reaching about 9.6 trillion riyals in July 2026, spread across 260 companies, according to Tadawul's weekly report. Any rule affecting where Saudis trade their money impacts this market's liquidity.
According to Saudi Tadawul data, the value of trades in foreign markets via Saudi brokers increased by 145% between Q4 2024 and Q4 2025, starting from 105.7 billion riyals. Meanwhile, client assets increased by only 60%, from 22.4 to 35.8 billion riyals. In Q1 2026, trading reached 264.4 billion riyals, including 241.9 billion riyals in US markets—about 91.5%, according to Saudi Tadawul data.
What does the proposal suggest?
The project receives comments via the Istitlaa platform until October 27, 2026, and will enter into force in its final form on November 1. According to the public consultation published by the Capital Market Authority on September 26, the client is required to maintain a margin of not less than 50% of the transaction value before execution, monitored daily so that it does not fall below 25% of the current position value. Margin financing for leveraged funds and paper, commodity- and metal-linked instruments, volatility indices, and shares of companies whose accumulated losses reached 50% or more of their capital is prohibited. It also adds suitability requirements, independent written approval to lend client shares, and for benefits arising from payments for order flow.
These ratios are already applied within the Kingdom. Article 45 of the Capital Market Institutions Regulations imposes an initial margin of not less than 50% and a maintenance margin of 25% of the current value of each position in locally listed company shares. The proposal thus extends local market logic abroad.
Protection or Guardianship?
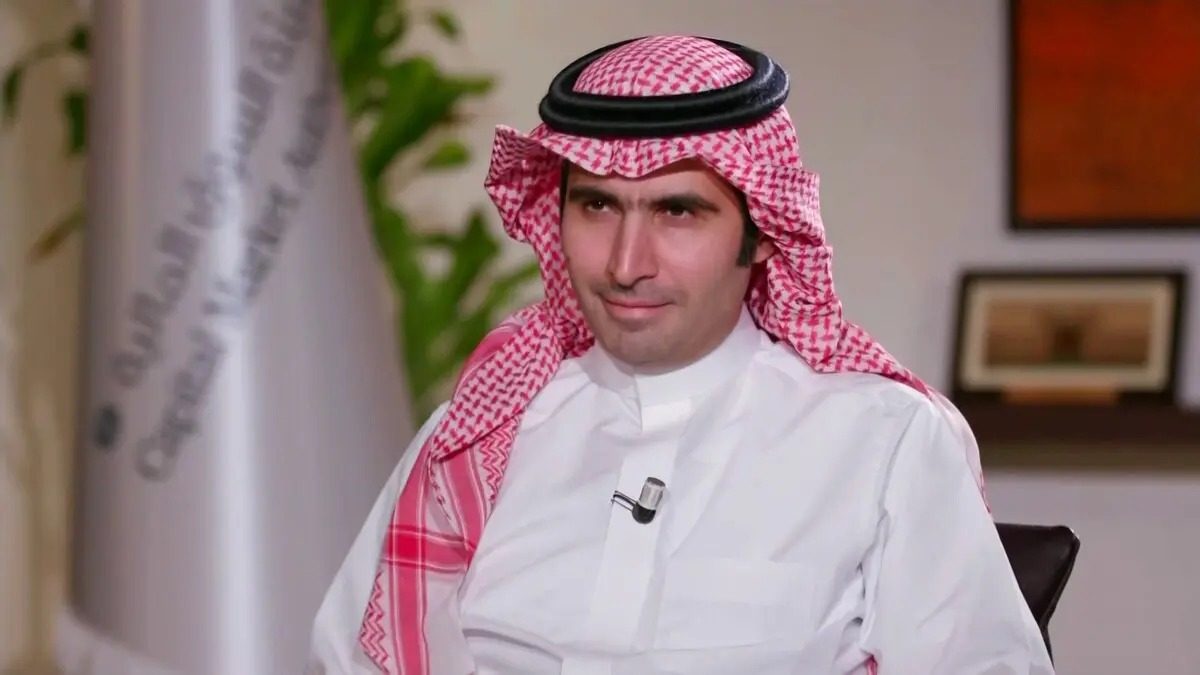
Perhaps what CMA Chairman Mazen Al-Sudairi told Al Arabiya channel, in his first media appearance after taking office, puts this proposal testing the limits of CMA intervention: Where does investor protection end and guardianship over them begin? Al-Sudairi stressed that the CMA's role is not to make decisions on behalf of the investor, but to protect them from the risks of high-leverage products, which are products that may lead to losses exceeding the invested capital.
However, investor protection is not measured by restrictions alone; the narrower their options become within the licensed framework, the more important it is for the market to offer understandable and competitive alternatives, so they do not seek leverage in less regulated channels.
Al-Sudairi presented opening the market to foreigners as part of a broader vision to rebuild the market and enhance its competitiveness, not a separate decision limited to increasing the number of investors. His vision aims for a market that serves as a destination for citizens' savings while attracting international capital, under a program that includes offering quality, algorithmic trading, and short-selling controls.
The most pressing question after all these statements is how the decision will impact liquidity. The proposed restrictions will not automatically return funds traded abroad to the local market. Setting margin limits reduces leverage, and foreign trading volume may fall in the first phase, but money stepping back from leverage does not necessarily head to Tadawul. What is required is a change in liquidity quality, reducing the impact of margin calls and forced selling during downturns.
As for the domestic front, Al-Sudairi diagnosed the problem himself: a large number of declining stocks, weak offerings, low trading volumes, and a changing trader demographic. He mentioned that a large portion of algorithmic trading stems from foreign institutions and that the CMA is monitoring it. Restricting leverage abroad addresses none of this. For Saudi investors to remain in their market, they need stocks that yield returns post-listing and clearer disclosures.
The most prominent trap in the interview was Al-Sudairi's evasion of answering his toughest question: Will the foreign share increase? According to Al-Sudairi's statements, there is no decisive answer yet. He emphasized that the CMA is discussing with government entities and sectoral regulators to reach agreed-upon percentages before taking a decision, so as not to be forced to backtrack later. He did not announce an alternative percentage or date. The current ceiling is 49% for foreign investors combined and 10% for a single non-resident investor, excluding strategic investors. The review is serious and may result in percentages varying across sectors, but it has not turned into a decision.
The stakes are high. Foreign ownership reached only 4.66% of market capitalization as of July 23, 2026, despite opening the market to them in February. Morgan Stanley estimated, according to excerpts published by Bloomberg, that raising the ceiling to 75% could attract about $4.3 billion in index-linked flows, and eliminating it could raise them to $7.4 billion. This is a bank's estimate, not the CMA's position.
The proposal caps leverage abroad, but it does not grant the local market new liquidity. What will grant it liquidity is for Saudi investors, before foreign ones, to see a fair market with good listings, disciplined algorithmic trading, and stable rules. If that does not happen, some clients might seek higher leverage on unlicensed platforms—a potential risk not yet backed by published data.
These reforms earn the CMA a reputation for strictness before a reputation for openness. The market needs both. What will judge the CMA is not what it said before October 27, but what it will do after.
What do these terms mean?
Financial Leverage: Using borrowed money to magnify the size of a trade. With a 4:1 leverage, for example, you can control 400 riyals with just 100 riyals. Profit multiplies, and loss multiplies as well.
Initial Margin and Maintenance Margin: Initial margin is the collateral you deposit when opening a trade. Maintenance margin is the minimum balance that must remain in your account, otherwise the trade is closed automatically.
Leveraged Securities: Financial instruments such as futures and options that allow controlling assets worth far more than the paid-up capital.
Margin Financing: A service provided by the broker allowing the client to purchase securities with money partially borrowed from the broker, against interest and secured by the purchased securities.
Foreign Trading: Buying shares in markets outside the Kingdom through licensed Saudi brokers. The current proposal specifically limits leverage in these transactions.
Index-linked Flows: Funds from passive investment products that automatically buy and sell stocks when added to or removed from major indices, such as the MSCI Emerging Markets Index.
Beyond The Number
"MNT-Halan": 124.8k Lawsuits in the Prospectus of the Largest EGP IPO... Does the Price Compensate the Investor for the Risks?
Saudi Arabia Between a Widening Deficit in 2026 and Declining Spending in 2027: Is Vision 2030 Entering Its Toughest Test?
Algorithms in Saudi Arabia and Telegram Recommendations in Egypt... Who Protects Retail Investors?
"خطة الشطرنج".. هل ينجح البنك المركزي المصري في إنقاذ المصانع المتعثرة؟
Weekly Newsletter
Read between the lines before everyone else. Decode the most important economic, tech, and decision-maker movements in the region.. in 5 minutes every Saturday.