56 Pounds to the Dollar: What Do the Figures Reveal About Hot Money? And Will It Jump to 70?
Summary
Coinciding with the movements of foreign portfolio funds and negotiations over the $5.3 billion Saudi deposit, this article tracks foreign sales and their pressure on the Egyptian pound, then assesses the likelihood of the dollar reaching 70 pounds.
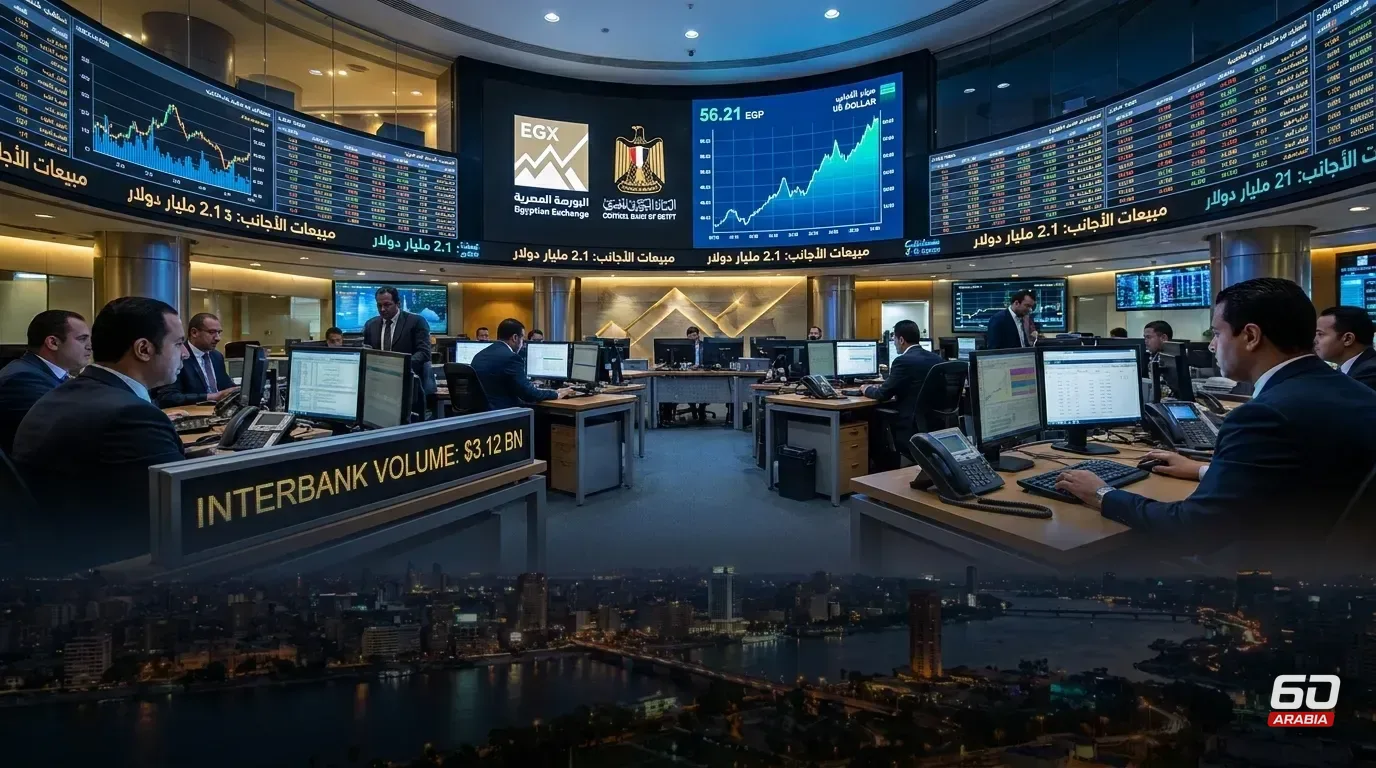
In the span of two weeks, three figures converged on the Egyptian market screen: a notable jump in the dollar crossing the 56 pounds barrier for the first time, net foreign sales in debt instruments of about $2.1 billion in a single week, and interbank trading reaching $3.12 billion. From these numbers, a rapid narrative is taking shape regarding the exit of hot money, to which a fourth unverified figure circulating without official backing is added: $3.2 billion in four days. This article puts each figure in context: what the published data proves, what it leaves unresolved, and whether the dollar will reach 70 pounds. More accurately from the outset, the available data measures foreign sales in debt instruments and their pressure on the exchange market, whereas the net amount actually transferred abroad is not settled by public data.
The Dollar Breaks the 56 Pounds Barrier: A Jump of About 7.5% in Three Weeks
The dollar broke the 56 pounds barrier on October 26, recording at the Central Bank around 56.21 for buying and 56.35 for selling, after standing at around 52.3 pounds at the beginning of the month. By my calculation, this represents a jump in the dollar price of about 7.5%. The official rate announced by the Central Bank on the morning of October 28 stood at around 56.05 for buying and 56.19 for selling.
Debt Sales Do Not Mean Money Has Left Egypt
According to Egyptian Exchange data, foreign investors sold treasury bills and bonds with net sales of about 73.8 billion pounds between October 19 and 21, while Egyptian investors bought about 12.6 billion pounds of them, bringing the combined net sales of both groups to $1.13 billion. Preliminary data for Thursday, October 22, recorded foreign selling of about 39.2 billion pounds, but it covers all securities, not debt alone, so I do not combine it with the previous figure.
On a weekly level, the secondary debt market recorded a net foreign outflow of about $2.1 billion alongside net Arab purchases, following two weeks of net inflows. These reports do not specify the exact days of the week, so I am not adding this figure to the October 19–21 window.
Then come preliminary data for two subsequent sessions, which I cite with context: net sales by foreign and Arab investors reached about $664.3 million in treasury bills and bonds on October 26 up until 4:00 PM, and about $619.1 million on October 27 up until 5:00 PM despite the pound's partial recovery. I do not sum these up because each figure is cut off at a different hour and may be subject to revision. Above all, these are sales in the secondary market and do not necessarily represent an immediate transfer of currency abroad.
Interbank: $3.12 Billion Total Trading Between Banks
Interbank transactions reached about $3.12 billion in the week ending October 22, compared to $1.93 billion in the previous week, well above the usual weekly average of between $750 million and $1.2 billion. However, this is total buying and selling between banks, not net outflows, and the figure is reported from sources rather than an official statement.
Funds Returned in Five Months and Are Tested Again
S&P estimated foreign holdings of Egyptian pound government securities at about $34.5 billion in September, compared to $22.2 billion in April, below the peak of $39.1 billion recorded in February. The agency estimated portfolio outflows following the outbreak of the regional war at about $9.5 billion. I do not compare the weekly figure with these balances and estimates, as the instrument, timeframe, and reporting entity differ, making an accurate ratio impossible. What the time series allows us to conclude is that significant funds returned within months and are now moving again.
Record Reserves vs. Current Account Deficit of $22.5 Billion
Net international reserves reached $57.35 billion in September, according to preliminary Central Bank data. In fiscal year 2025/2026, remittances from Egyptians abroad reached $47.3 billion, and foreign direct investment reached $18 billion. According to the Central Bank's balance of payments report, the current account recorded a deficit of about $22.5 billion, while net capital and financial inflows reached $23.2 billion, including portfolio investments of about $4.2 billion, with the overall balance recording a surplus of $2.8 billion. The difference between the first two numbers does not equal the overall surplus, as the balance includes other items I have not detailed here. The significance I draw is narrower: incoming capital and financial flows exceeded the current account deficit, though part of these flows remains volatile.
Here, the brilliant British economist John Maynard Keynes comes to mind. In 'A Tract on Monetary Reform' (1923), he criticized relying on long-term equilibrium to explain present disruptions, offering his famous phrase: "In the long run, we are all dead." Record reserves provide genuine reassurance, but alone they do not answer what the dollar rate will be this week.
The $5.3 Billion Deposit: An Open File Without Final Announcement
The obligations for the Saudi deposit due in October total $5.434 billion, consisting of $5.3 billion in principal and $134.8 million in interest (Central Bank External Position Report). According to a source quoted by Asharq Bloomberg, negotiations are focused on the renewal period without a final agreement reached by publication time. This does not imply non-renewal, but the absence of an official announcement leaves room for speculation.
Will the Dollar Jump to 70 Pounds? Conditional Warnings, Not Institutional Forecasts
I distinguish between four types of statements, all published this week. First, conditional warnings by some analysts that if the price stays above 56 without falling back within 48 hours, or if it crosses 57, it could push towards 65 and then into the 70 to 72 range. The rate remains above 56, but has not crossed 57.
Second, a conditional warning by economist Hany Genena regarding the possibility of surpassing 60, 70, and 80, but under a scenario responding to pressures of dollar liquidity injections.
Third, institutional estimates: Capital Economics stated in a note dated October 26 that the drop is manageable, forecasting 60 pounds by the end of 2027 if energy prices fall. Their end-of-2026 forecast was 55, a mark the price surpassed ahead of schedule, serving as a reminder of the limits of forecasting. Fourth, a year-end range: scenarios ranging between 52 and 57 pounds cited by Al Khaleej newspaper from CNN Business on October 27.
Historical comparisons also have their limits. The dollar reached around 70 pounds on the black market during the peak of the early 2024 crisis, but that was under a fixed official exchange rate and severe currency shortages—a situation different from today's flexible exchange rate. Following the March shock, S&P noted that rapid policy responses stabilized markets and reversed a large portion of the volatility.
As for my assessment, I found no baseline scenario of 70 pounds to the dollar in the institutional forecasts I reviewed. I view it as an extreme stress scenario whose probability or timeline cannot be determined from available data.
Prices and Interest Rates: How the Dollar Reaches the Citizen
Monthly core inflation accelerated to 0.8% in September compared to 0.3% in August, and the impact of the dollar reaches prices quickly. The interest rate decision is due tomorrow, Thursday, with 11 financial institutions expecting rates to be held steady. That is a projection, not a decision.
Three Demands to Block the Path of Rumors
I call on the Central Bank of Egypt and the Ministry of Finance to publish flow and interbank data using a declared methodology, gradually increase the maturities of new domestic debt issuances while reducing reliance on short-term T-bills, and announce the status of the Saudi deposit as soon as it is settled. When official numbers are absent, baseless figures fill the void.
The popular proverb "Only its stones remain in the valley" applies well to short-term portfolio flows, which can shift with yield and risk. What is far more sustainable is diversifying foreign currency sources, boosting exports and productive investment, alongside remittances.
Ibrahim Gamal Ibrahim is an Egyptian journalist and expert in digital media, economic and financial journalism, with more than 20 years of experience across the Middle East and North Africa (MENA) markets. He specializes in leading editorial teams, developing content and digital growth strategies, and integrating artificial intelligence into newsrooms, with extensive experience covering financial markets, monetary policy, and the banking sector. He has held editorial positions at Argaam, Veto, Besraha, Al Mal, and Mubasher.
Profile and all their articlesBeyond The Number
Sawiris's Hand Is in Water While the Small Investor's Hand Is in Fire... Is the Dip Really a Buying Opportunity?
Saudi Arabia and the Fifteen-Year-Old Trader: Who Draws the Blanket's Boundaries and Who Bears the Loss?
Banque du Caire at the Two Caps: The Vote Is Settled and the Market Test Begins After Trading
500 Riyals for a Lower Bill: Saudi Arabia Precedes 2027 Budget with a Support Package of Unannounced Cost
Weekly Newsletter
Read between the lines before everyone else. Decode the most important economic, tech, and decision-maker movements in the region.. in 5 minutes every Saturday.